Aerial view of a suburban Chicagoland neighborhood after a summer storm season

When the storm is over, the claim is just starting.

LDJPA is a public adjusting firm for homeowners and building owners in Chicagoland and northwest Indiana. We read the policy, document the loss and present the claim to your insurance company. We work for you, not the carrier.

LDJPA, Public Adjusters
Illinois Public Adjuster License: number on file once issued
Indiana Public Adjuster License: number on file once issued

Wind, hail, water and fire claims. Residential and commercial. Cook, DuPage, Will, Lake, Kane and McHenry counties in Illinois; Lake and Porter counties in Indiana.

Your insurance company sends its own adjuster. A public adjuster is the one who works for you.

What a public adjuster does

A public adjuster is licensed by the state to represent the policyholder, not the insurance company, in a property insurance claim. The adjuster your carrier sends is paid by the carrier. We are hired by you and we answer to you.

We start by reading your policy in full, including the endorsements and the exclusions most people never open. Then we go to the property, photograph and measure the damage, and write a line-item scope of the loss. We present that scope to your insurance company and handle the back and forth with their adjuster, so you are not the one on the phone explaining your own roof.

The first look is free. If your claim already looks fairly paid, we will tell you it is fairly paid and you owe nothing. If we can help, our fee is a percentage of what the policy pays, put in writing before anything starts. We do not repair anything and we never arrange repairs; who fixes your property is your decision.

Claims we take

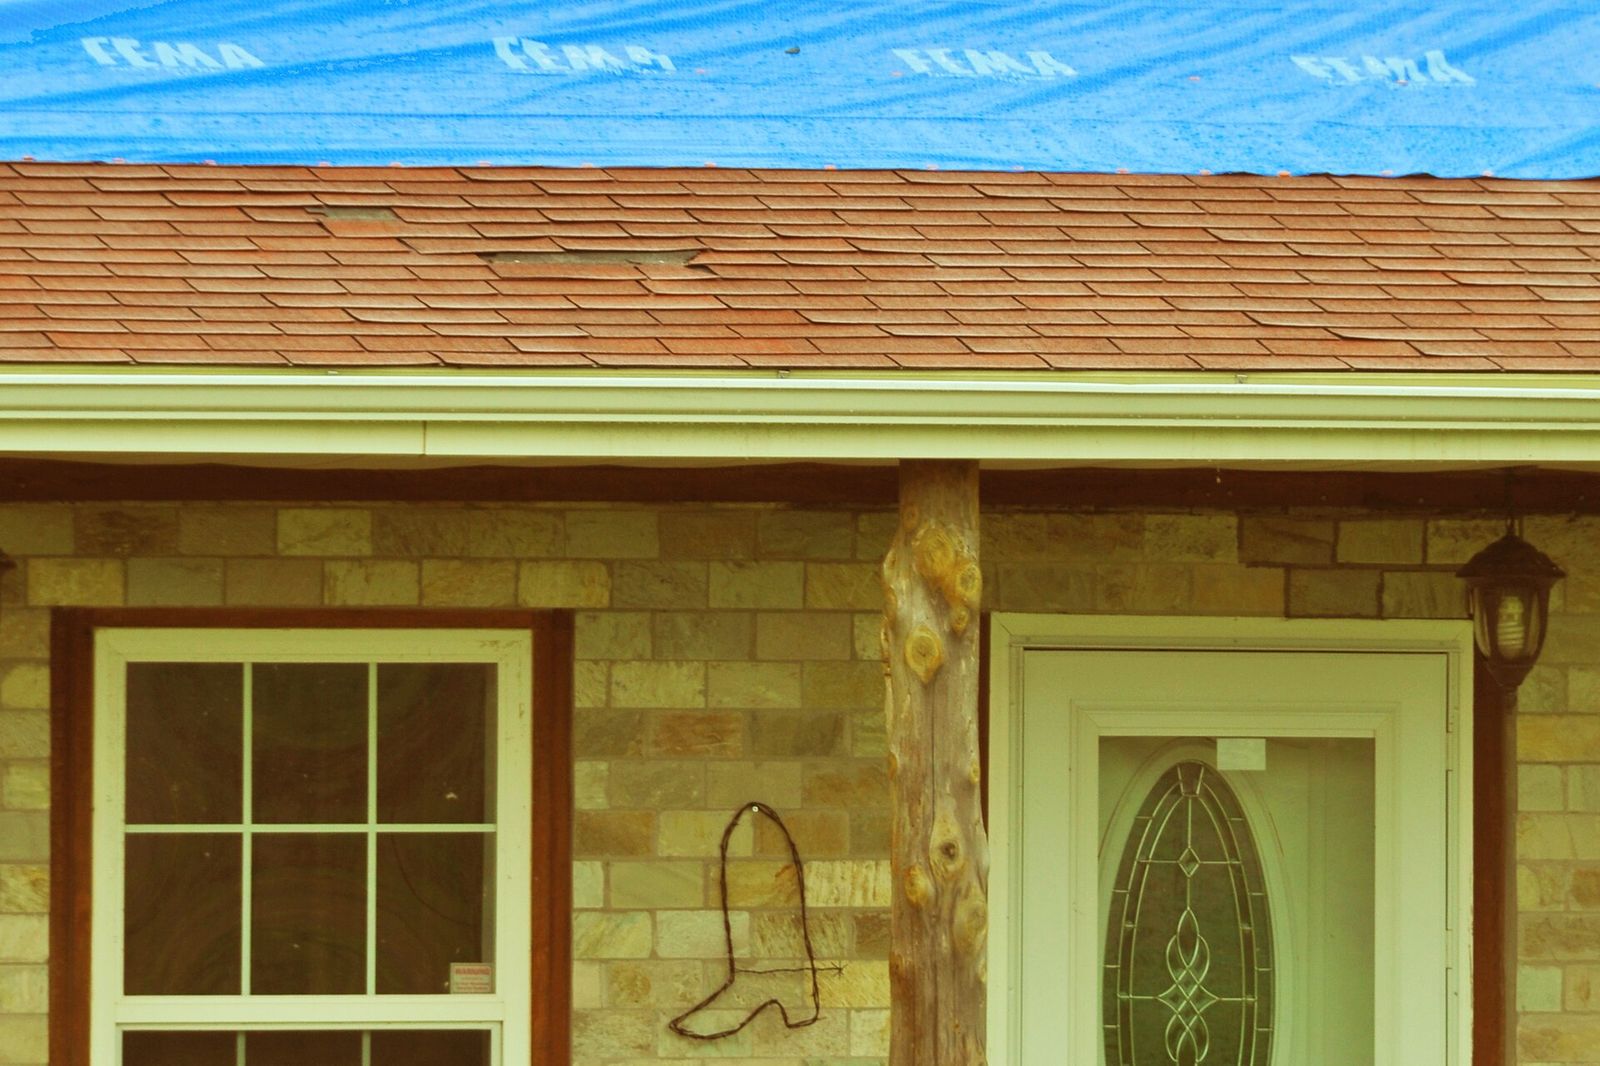
  • Wind and hailRoofs, siding, gutters, windows, and the interior damage that follows when water gets in. Most of what we see in Cook and DuPage starts here, May through September.
  • Water and pipeBurst pipes, failed supply lines, ice dams and sudden leaks. Coverage turns on the policy wording, so we read it before we say anything.
  • Fire and smokeStructure, contents, smoke and soot cleaning, and the cost of living elsewhere while the property is rebuilt.
  • Commercial propertyStrip retail, warehouses, offices and multi-family. Bigger roofs, more line items, and business income questions that need the policy read closely.
  • Denied or underpaid claimsA denial letter is a position, not a verdict. We check the reason given against the policy and the damage on site.

Where we work

Chicagoland and across the state line into northwest Indiana. We come to the property.

  • Cook County, IL
  • DuPage County, IL
  • Will County, IL
  • Lake County, IL
  • Kane County, IL
  • McHenry County, IL
  • Lake County, IN
  • Porter County, IN

Elsewhere in Illinois or Indiana? Call. If it is a property claim and we can get there, we will look at it.

How it works

Five steps, in the order they happen. Nothing is signed until step two, and nothing is accepted without you.

  1. 1

    Call or send the form

    Tell us what happened, when, and what the carrier has said so far. Keep every letter and estimate they sent you.

  2. 2

    Free first look

    We read your policy and the carrier's estimate at no cost. If the claim is fairly paid, we say so. If we can help, we put our fee in writing and you sign before any work begins.

  3. 3

    We document the loss

    We come to the property, photograph and measure the damage, and write a line-item scope. Where the policy language matters, we quote it.

  4. 4

    We present it to your carrier

    We send the scope and the documentation to your insurance company and handle the communication with their adjuster. If they disagree, we answer with evidence.

  5. 5

    You decide

    Every offer comes to you with our read on it. You accept or decline. We never settle a claim on your behalf without your say, and our fee comes out of the payment at the percentage in your contract.

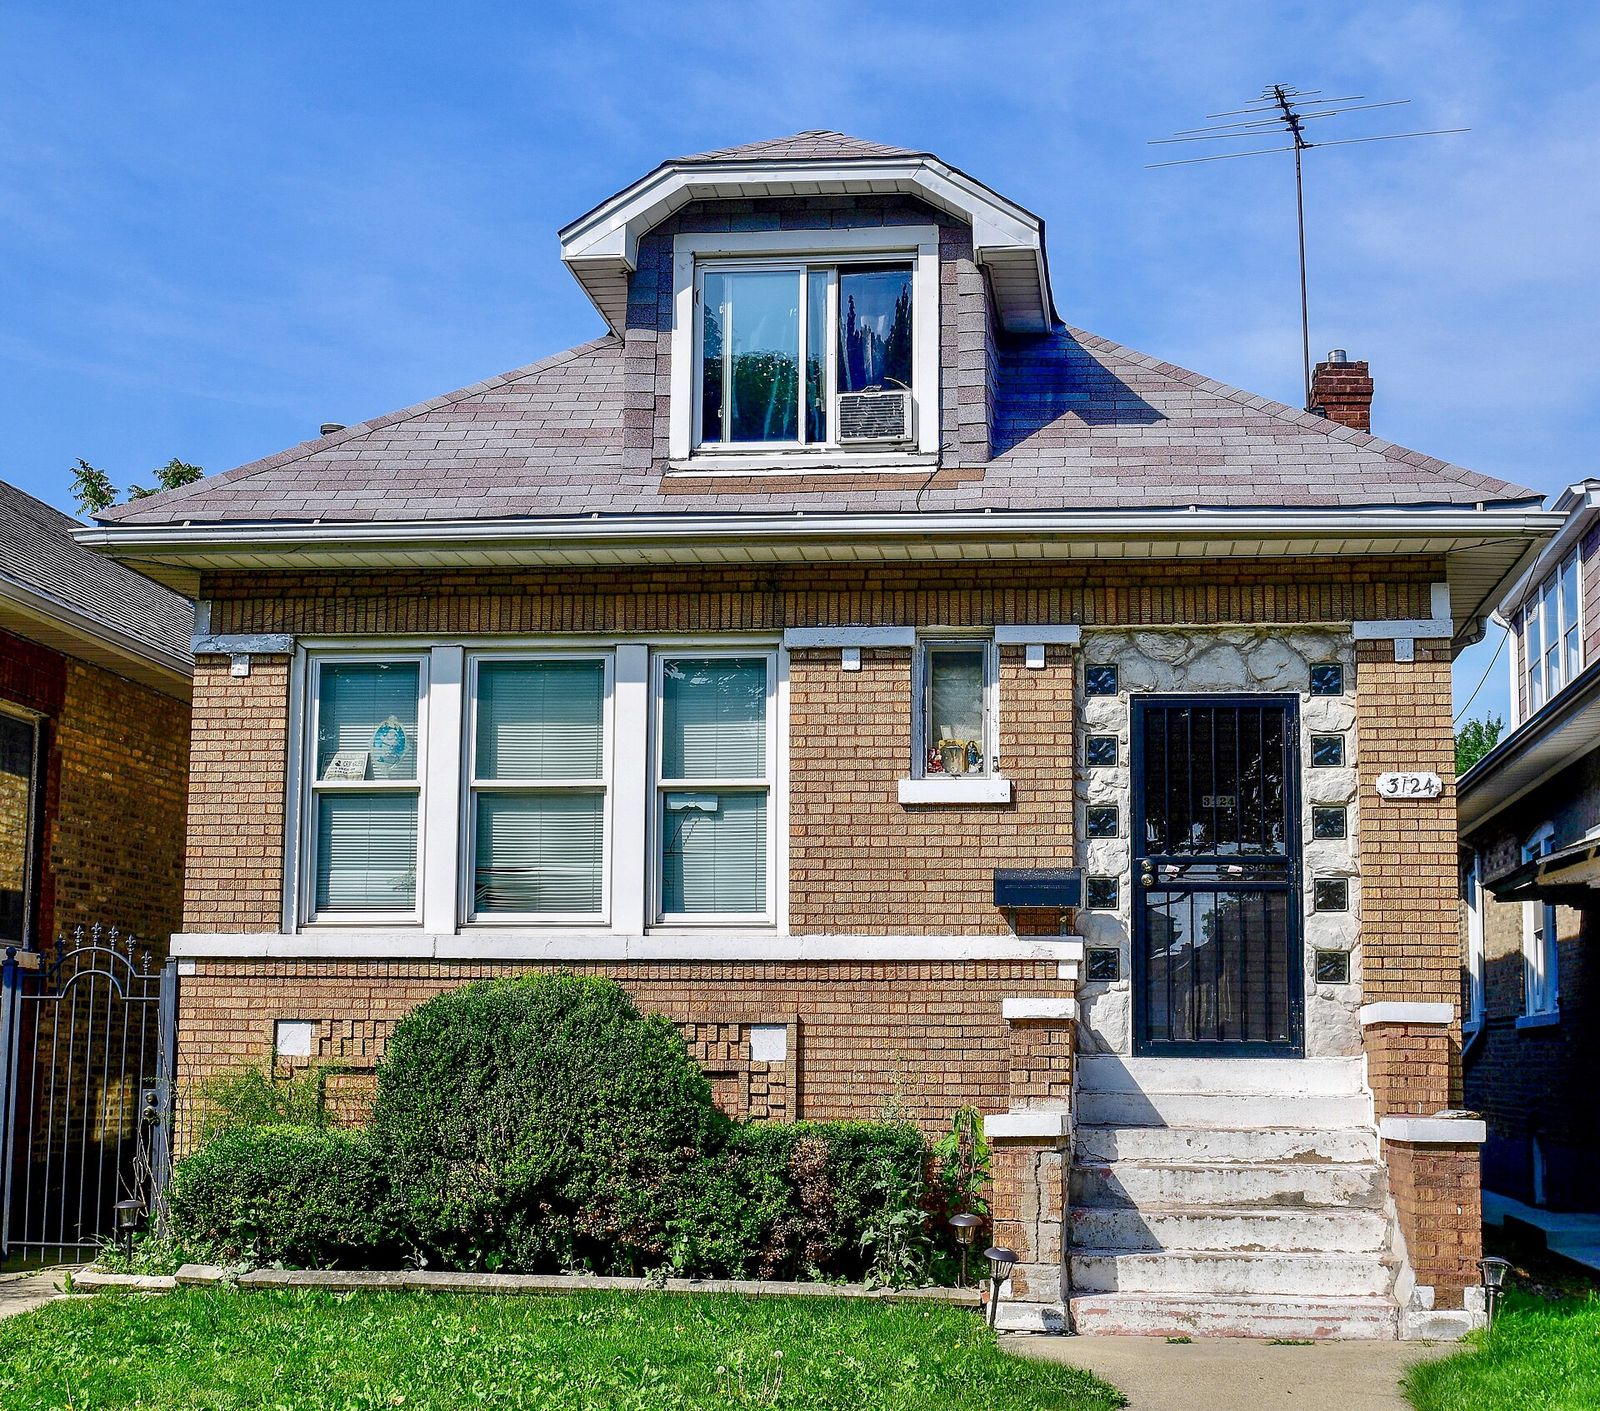
A brick Chicago bungalow on the South Side
Stock photo for the preview. Carlos's own photo goes here.

About Carlos

I have run a licensed Illinois roofing company and I have read roofs from the ladder for years. I know what hail does to a shingle, what wind does to a ridge, and what it costs to put a roof back the way the policy says it should be. I started LDJPA because too many owners around here sign off on the first number they are handed.

I read the policy myself, I write my own scopes, and I meet you at the property. If I think your claim is already fairly paid, I will tell you so, and you owe me nothing for the look.

Carlos, LDJPA
Your rights as a policyholderYou may cancel a public adjuster contract within the period stated in the contract. In Illinois you are never required to use a specific contractor for repairs, and we will never name one. Read every page before you sign, including ours.

Reviews & Gallery

LDJPA is a new firm. Reviews will appear here, with the reviewer's first name, town and date, once the Google Business Profile is live.

Read all reviews on Google. Link to the LDJPA Google Business Profile goes here once the profile is verified.

Start with a free first look

Tell us what the carrier said. We read the policy first and tell you plainly whether we can help. Calls are returned the same day.

No cost and no obligation for the first look. We do not sell or share your information.

Call or text

(000) 000-0000

Email

Business email to be set up

Office

Town to be confirmed, IL
By appointment. We come to the property.

Call (000) 000-0000Free first look